Conversion in progress ...
Please wait while we generate your PDF
The South Florida Home Buyer’s Guide
START WITH THE RIGHT SEARCH
Finding homes online is easy. Knowing which ones are actually worth pursuing is where the work begins.
Before getting serious about individual properties, define the things that really matter: location, property type, budget, monthly carrying costs and how you plan to use the property. For condos, that can also mean looking beyond the unit itself at the building’s financial health, reserves, assessments, insurance, rental restrictions and other factors that can affect both ownership and resale.
A well-designed search helps narrow the field, but it shouldn't be so rigid that you miss a property worth considering. Sometimes the best opportunity checks every box. Sometimes it requires recognizing which compromises matter—and which ones don't.
The goal isn't to see the most properties. It's to identify the right ones and understand what you're buying before you make an offer.
GET YOUR FINANCING IN ORDER EARLY
If you're financing your purchase, getting pre-approved before you become serious about a property gives you a much clearer picture of what you can comfortably buy—and puts you in a stronger position when it's time to make an offer.
But don't focus only on the interest rate. Compare the overall loan structure, estimated closing costs, lender fees and the experience of the person handling the loan. A good lender should also understand the South Florida market and the types of properties you're considering.
That matters especially with condominiums. A buyer may qualify for a loan while a particular building does not. Reserves, insurance, pending assessments, litigation, owner occupancy and other building-level issues can sometimes affect available financing.
Before you fall in love with a property, make sure both sides of the equation work: your financing and the property you're trying to finance.
MAKE THE OFFER FIT THE SITUATION
There isn't one formula for making a successful offer. The right strategy depends on the property, the seller, how long the home has been on the market, recent comparable sales, competing interest and your own priorities.
Price matters, but it isn't the only thing a seller may consider. Financing, deposit size, inspection terms, closing date and other contingencies can all affect the strength of an offer. Sometimes flexibility on the right term can be more valuable than simply increasing the price.
Just as important, don't let competition push you into ignoring the property's value or taking risks you don't fully understand. A strong offer should be competitive enough to accomplish your goal while still protecting your interests.
The objective isn't simply to “win” the property. It's to buy the right property on terms that still make sense after the excitement of the negotiation is over.
UNDERSTAND YOUR TOTAL COST TO CLOSE
The purchase price isn't the only number that matters. Before making an offer, understand how much cash you'll actually need to complete the purchase.
Depending on the transaction, that can include your down payment, lender costs, inspections, appraisal, title-related expenses, prepaid taxes and insurance, escrow deposits and other closing costs. Condo and homeowners association requirements can add additional expenses as well.
In some situations, a seller contribution toward closing costs may make sense. In others, asking for a credit could make your offer less competitive or simply shift the economics elsewhere in the negotiation. The right approach depends on the property, your financing and the circumstances of the sale.
Know the full financial picture before you negotiate—not after your offer is accepted.
UNDERSTAND THE MARKET YOU'RE BUYING IN
South Florida isn't one real estate market. Conditions can vary considerably from one neighborhood, building and property type to another—even within a few miles.
A condo in Miami Beach may be experiencing very different supply and demand than a single-family home in Pinecrest. Two buildings across the street from each other can perform differently because of reserves, assessments, insurance, amenities, rental policies or simply buyer preference.
That's why broad headlines about whether it's a “buyer's market” or “seller's market” only tell part of the story. What matters more is the competition, recent sales, available inventory and pricing trends for the specific type of property you're considering.
Timing can matter, but understanding the market directly in front of you is usually more valuable than trying to time South Florida as a whole.
LOOK BEYOND WHAT YOU SEE AT THE SHOWING
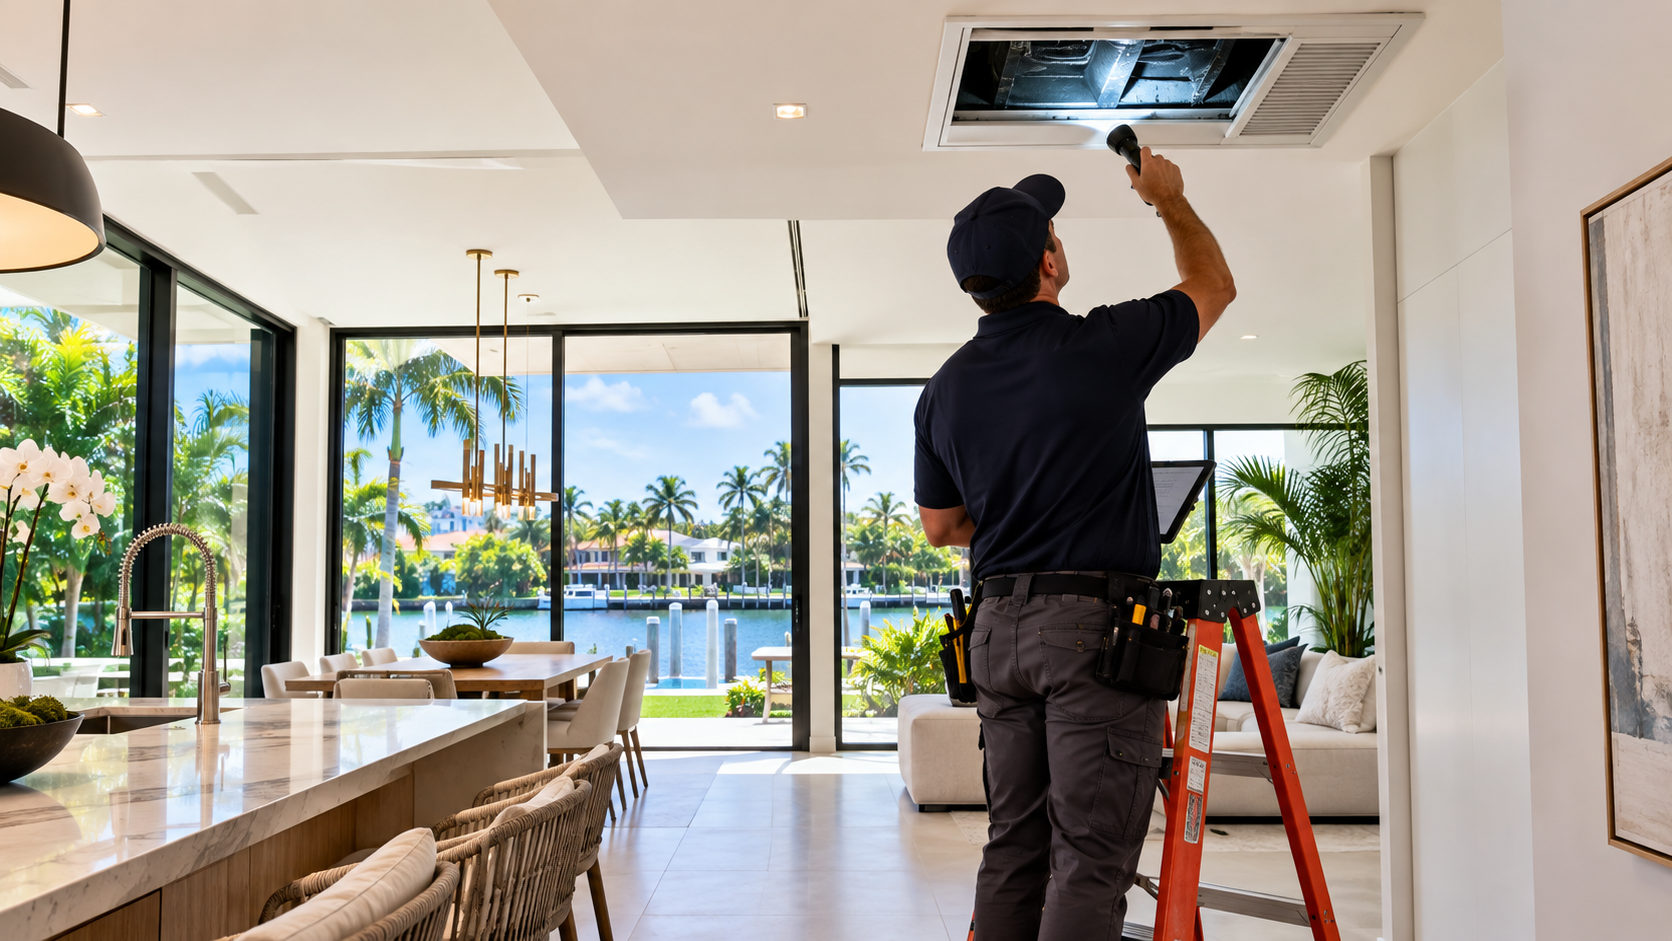
A property can look great and still have issues that aren't obvious during a walkthrough. Once you're under contract, the inspection and due-diligence period is your opportunity to take a closer look before moving forward.
A professional inspection can help identify concerns involving the roof, electrical and plumbing systems, air conditioning, structure, appliances and other components of the property. In South Florida, age and condition can also affect insurability and the cost of coverage, making items such as the roof, electrical system and hurricane protection particularly important.
The inspection isn't simply about creating a repair list. It's about understanding the condition of the property, identifying potential expenses and deciding whether anything you discover changes the value—or your willingness to buy it.
A beautiful property can still be a bad purchase if you don't understand what comes with it.
WHEN BUYING A CONDO, YOU'RE BUYING MORE THAN THE UNIT
A beautifully renovated condo can be a great purchase—or a very expensive mistake if you only evaluate what's inside the unit.
Before buying, it's important to understand the financial and physical condition of the condominium association. That can include reviewing budgets, reserves, existing or proposed special assessments, insurance, major planned repairs, litigation and other association documents. Depending on the building, structural inspection requirements and reserve studies may also provide important information about future expenses.
Rules matter too. Rental restrictions, pet policies, parking, approval requirements and other regulations can affect how you use the property today and how easy it may be to sell or rent in the future.
No building is perfect, and the existence of an assessment or upcoming project doesn't automatically make a condo a bad purchase. What matters is understanding what you're taking on, what it may cost and whether the building still makes sense for you.
CONSIDERING NEW CONSTRUCTION? UNDERSTAND THE TRADEOFFS
New and pre-construction properties can be appealing: modern design, newer building systems, updated amenities and the opportunity to be among the first owners. But buying from a developer is different from purchasing a resale property.
With pre-construction, you're often making decisions based on plans, renderings and specifications rather than a finished home. Deposit schedules can extend over months or years, completion dates can change, and the finished property or surrounding neighborhood may not look exactly as you imagined when you signed the contract.
Developer contracts also deserve careful review. They are generally written to protect the developer, and the terms, cancellation rights, closing requirements and flexibility available to a buyer can differ substantially from a typical resale transaction.
New construction can absolutely be the right choice. Just evaluate the developer, the project, the contract, the timeline and the total cost—not simply the renderings and sales presentation.
DON'T OVERLOOK INSURANCE AND FLOOD RISK
As you know, every homeowner in the US must pay his/her yearly property taxes. But if they fail to pay these taxes, their name is added to the county’s treasurer’s “Tax Delinquent List.”
If enough time goes by (1-5 years) and the homeowner doesn’t pay those delinquent taxes, the county takes possession of the home via a tax foreclosure. Then, the house is auctioned off to recuperate those missing taxes (from which the homeowners would get $0 in return).
Believe it or not, tax delinquent lists are part of the public record. You can have access to your local list by asking for it in your county treasurer’s office, and paying a fee to obtain it.
This list is filled with homeowners that have a HUGE motivation to sell their property, especially if they haven’t paid their property taxes in years. If they’re only a year or two away from losing their home to a tax foreclosure, and they could be willing to sell their home or property for pennies on the dollar.
Of course, as you may expect, many of these homes fall squarely into fixer-upper territory, and would require you to have plenty of capital to get them into shape.
KNOW WHAT HAPPENS BETWEEN CONTRACT AND CLOSING
Getting an offer accepted is exciting, but there is still plenty to do before the property is yours.
Once you're under contract, several things may be happening at the same time. Your deposit will be due according to the contract, inspections and other due diligence need to be completed within specific deadlines, and if you're financing, your lender will be working through underwriting and the appraisal.
This is also when issues that weren't obvious during a showing can come into focus. Depending on the property, that may include inspection findings, insurance concerns, title matters or, with a condominium, association documents, financials, assessments and approval requirements.
As closing approaches, you'll review the final numbers, complete a final walkthrough and make sure the remaining contractual requirements have been satisfied.
The period between contract and closing isn't just a waiting period. It's when many of the details that protect your purchase are worked through—and deadlines matter.
THE RIGHT GUIDANCE MATTERS
Buying real estate involves more than finding a property you like. The right guidance helps you evaluate the property, understand the market around it and recognize issues that may not be obvious at first glance.
That can mean analyzing comparable sales before making an offer, understanding the strengths and weaknesses of a particular building or neighborhood, reviewing condominium financials and assessments, coordinating inspections and financing, and helping you make informed decisions as the transaction moves toward closing.
After nearly 30 years in South Florida real estate, I've learned that every purchase is different. My role isn't to push you toward a property or simply get a deal done. It's to give you the information, perspective and candid advice you need to decide what's right for you.
READY WHEN YOU ARE
You don't need to have everything figured out before starting a conversation.
Whether you're actively looking, still deciding where in South Florida you want to be, or simply trying to understand what your budget will buy, I'm happy to help you sort through the options.
When you're ready, let's talk about what you're looking for and what makes sense for you.